
Explore the latest free tools from the MQL5 community. Here's a new indicator, expert advisor, or script for MetaTrader.
RegimeRouter — trend/range classifier with a per-regime win rate ledger
The problem
A trend-following rule loses money in a range. A mean-reversion rule gets destroyed in a trend. Most EAs pick one and hope the market cooperates. The usual fix is a single ADX filter. ADX measures one thing, directional strength, and says nothing about whether returns are actually persistent or mean-reverting.
Watch in-depth trading tutorials and EA reviews on the RobotFX YouTube channel. Subscribe for free tips.
How it classifies
On every closed bar it measures three independent properties of the recent price series.
- ADX
- Hurst exponent
- Lag-1 autocorrelation
Each casts a vote. Plus one for trend, minus one for range, zero for undecided. The votes are summed. If the sum clears
How it routes
| Regime | Module |
|---|---|
| TREND | Break of the N-bar high or low, taken only in the direction the fast and slow EMA are already pointing. |
| RANGE | Fade a stretched z-score of price against its own moving average. Buy the low tail, sell the high tail. |
| NEUTRAL | Nothing. |
The ledger
Every position is opened with a magic number of
For each module it reports the raw win rate, theWilson 95% lower bound, thebreakeven win rate implied by that module's own average win and average loss, the profit factor, and a verdict.
TREND 96 tr 38 W raw 39.6% wilson95 30.4% breakeven 34.2% PF 1.26 net +734.84 [UNPROVEN]
The middle two numbers are the ones that matter. A 2R trend follower is profitable above roughly 34%. A 1R fade needs better than 50%. And a raw win rate from six trades is not evidence of anything. The verdict is simply whether the lower bound clears breakeven, which is the only version of "this module works" that survives a small sample.
The A/B switch
InpForceRegime
Do that before trusting it. The routing idea is a hypothesis, not a result.
Backtest
H1 · 2026.01.01 to 2026.09.20 · 10 000 USD · Random delay enabled · all inputs at default. Two symbols, both shown.

EURUSD H1
| Metric | Value |
|---|---|
| Total net profit | +900.42 |
| Gross profit / gross loss | 3 712.84 / 2 812.42 |
| Profit factor | 1.32 |
| Expected payoff | 9.00 |
| Recovery factor | 1.71 |
| Total trades | 100 |
| Maximal balance drawdown | 505.32 (4.56%) |
| Maximal equity drawdown | 527.80 (4.76%) |
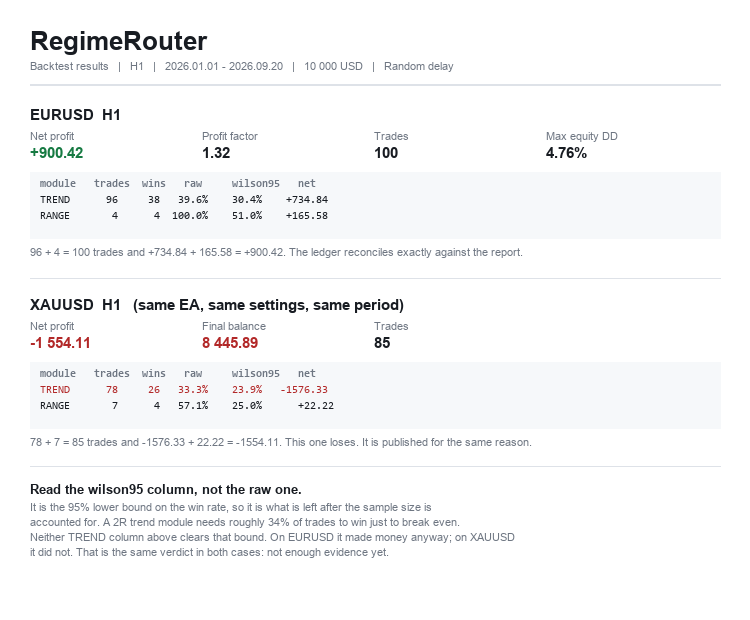
| Module | Trades | Wins | Raw | Wilson 95% low | Net |
|---|---|---|---|---|---|
| TREND | 96 | 38 | 39.6% | 30.4% | +734.84 |
| RANGE | 4 | 4 | 100.0% | 51.0% | +165.58 |
96 + 4 = 100 trades and +734.84 + 165.58 = +900.42, so the ledger reconciles exactly against the tester report.
XAUUSD H1 — same EA, same settings, same period
| Metric | Value |
|---|---|
| Total net profit | −1 554.11 |
| Final balance | 8 445.89 |
| Total trades | 85 |
| Module | Trades | Wins | Raw | Wilson 95% low | Net |
|---|---|---|---|---|---|
| TREND | 78 | 26 | 33.3% | 23.9% | −1 576.33 |
| RANGE | 7 | 4 | 57.1% | 25.0% | +22.22 |
78 + 7 = 85 trades and −1 576.33 + 22.22 = −1 554.11. This one loses money. I am publishing it next to the winner on purpose, because a listing that shows only the symbol that worked tells you nothing about the EA.
What that result does and does not show
Read this part before you use it.
- The TREND module is not proven on either symbol.
- It would take roughly 320 trades
- The RANGE module is essentially untested.
- There is no out-of-sample test.
- Modelling was "Every tick", not real ticks.
I am publishing it because the measurement apparatus is the useful part, not because I have a validated edge to sell you. Run the A/B. If the router does not beat its own two modules on your symbol, that is worth knowing too.
Execution notes
- Signals are evaluated on bar close, so this is built for M15 and higher.
- Positions open with no stops, then the stops are attached from the real fill price. A stop computed from a pre-trade snapshot can already be invalid by the time the order fills.
- If attaching the stops fails the position is closed immediately rather than left unprotected.
- Stop distances are clamped to the symbol's own stops level and freeze level.
- Exits belong to the broker's SL and TP. There is no manual timed force-close.
- Optional ATR trailing stop for trend trades, applied at most once per bar and never on the entry bar.
- One position at a time. On a netting account a second order on the same symbol merges into the existing position instead of becoming its own trade, which would silently corrupt the ledger.
- Risk-based lot sizing, a daily loss limit, a daily trade cap, a spread filter, a minimum take-profit-to-spread ratio, and an optional session filter.
Main inputs
| Input | Default | What it does |
|---|---|---|
| InpForceRegime | Auto | Force one module, to A/B the classifier |
| InpMinVotes | 2 | Votes out of three needed to commit to a regime |
| InpADXTrendLevel | 25 / 20 | ADX vote thresholds |
| InpHurstBars | 256 | Bars of returns behind the Hurst estimate |
| InpHurstAdaptive | off | Judge Hurst against its own distribution instead of fixed levels |
| InpAutoCorrThreshold | 0.05 | Autocorrelation must clear this to vote |
| InpBreakoutBars | 20 | Trend module: N-bar high/low to break |
| InpRangeZEntry | 2.0 | Range module: z-score at which to fade |
| InpRiskPercent | 0.5 | Risk per trade, % of balance |
| InpMagicBase | 772000 | Regime id is added to this |
Note on the Hurst threshold
There is an input called
The textbook trend/range line for the Hurst exponent is 0.5. In practice that line is in the wrong place. The R/S estimator is biased upward on a finite sample, so a 256-bar estimate of an ordinary series lands well above 0.5. Measured on EURUSD H1 the readings averaged 0.568 and dropped below 0.45 only twice in 419 observations. Against a fixed 0.45 / 0.55 band that voter is not measuring anything. It is a near-permanent vote for TREND.
Turning
The cost of that is real. By construction the voter then votes RANGE on a fixed share of bars whatever the market is doing. So it is a switch, not a rewrite. It is off by default because the backtests above were run with it off, and I do not want the shipped default to be a setting I have no results for.
No strategy is guaranteed to be profitable. This gives you a structure to test with the measurement built in. It does not give you an edge.
— Ali Rajput
Level up your trading with professional RobotFX expert advisors and indicators. Visit robotfx.org for proven MT4/MT5 tools.
77535


